Richemont half-year results: Jewellery drives growth as watch brands gain ground
Richemont continues its growth trajectory. In the first half of the 2026/27 financial year, Group revenue rose by 17 per cent to 12,3 billion euros.
At a Glance
- Richemont increases first-half revenue for 2026/27 by 17 per cent at constant exchange rates to 12,3 billion euros; jewellery remains the growth driver.
- Operating profit at the Specialist Watchmakers triples from 50 to 150 million euros; the operating margin adjusted for one-off effects stands at 7,7 per cent.
- Of relevance to independent specialist retailers: the Group’s own boutiques and online channels account for 78 per cent of revenue, two percentage points more than in the previous year.
While the jewellery maisons continue their exceptionally strong performance, the watch brands are also gaining considerable momentum. Vacheron Constantin, Jaeger-LeCoultre and A. Lange & Söhne are making a particular contribution to the recovery. Swiss luxury goods group Richemont published its results for the six months to 30 September 2026 on 13 November. Revenue rose by 17 per cent at constant exchange rates and by 16 per cent at actual exchange rates. Operating profit increased by 33 per cent to 3,1 billion euros, while profit for the period rose by 39 per cent to 2,5 billion euros. The operating profit performance does, however, include positive tariff-related one-off effects of 229 million euros. Adjusted for these exceptional items, the operating margin stands at 23,6 per cent rather than the reported 25,5 per cent.
Jewellery remains the principal growth driver
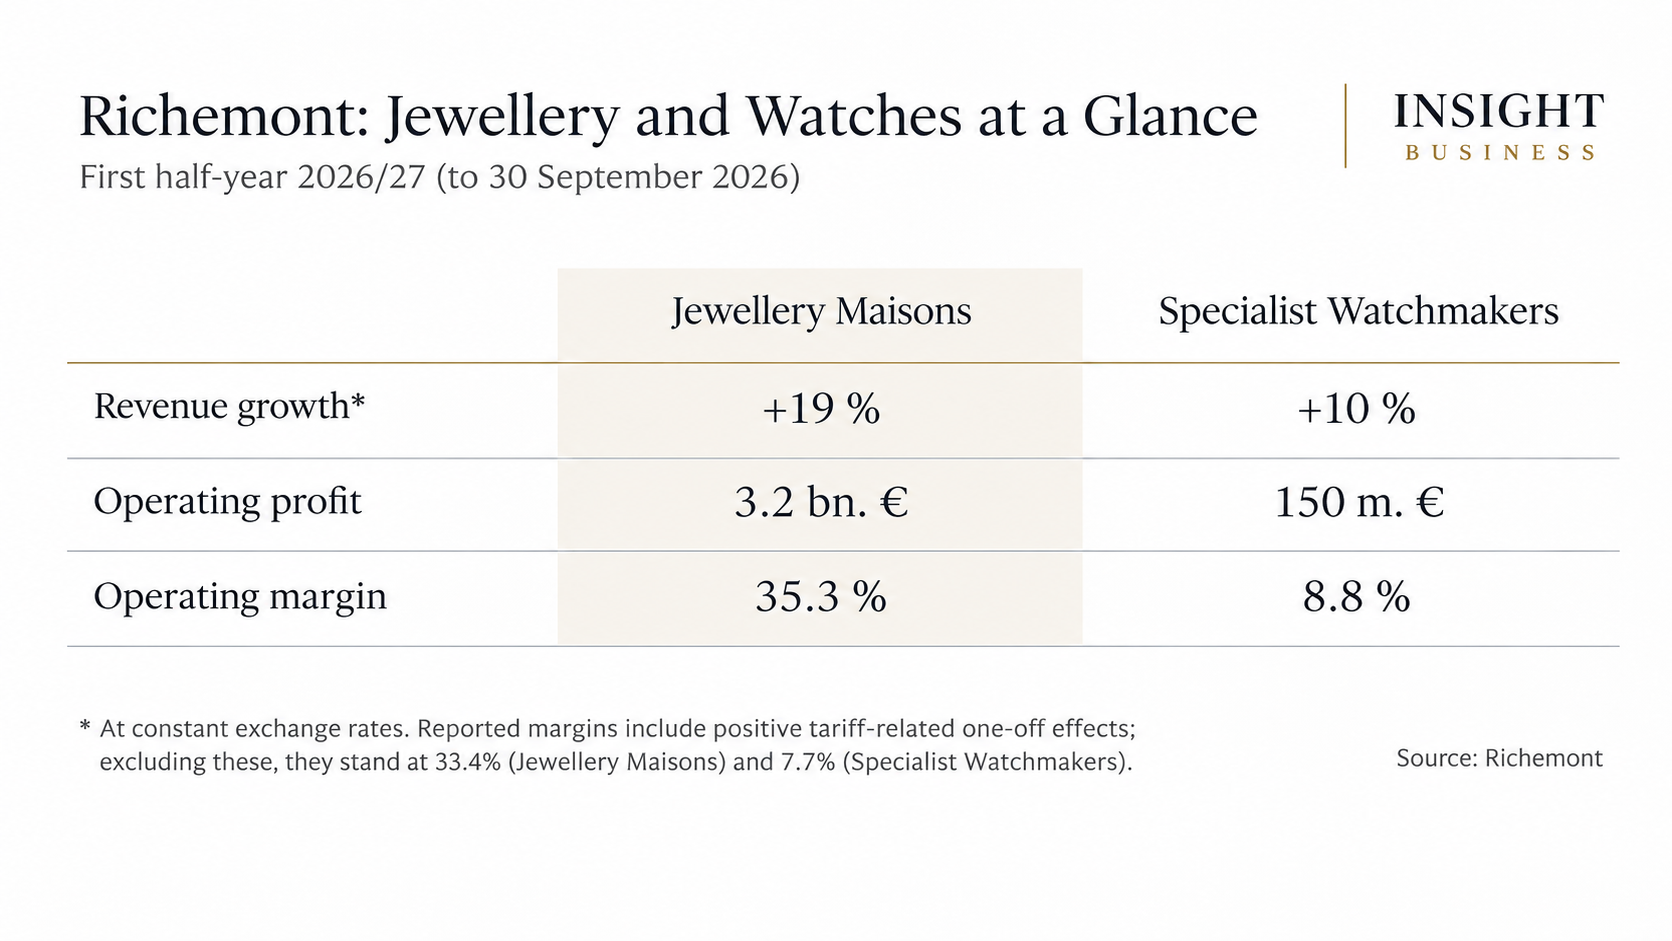
The Jewellery Maisons Cartier, Van Cleef & Arpels, Buccellati and Vhernier increased their revenue by 19 per cent at constant exchange rates. Their operating profit reached 3,2 billion euros, with an operating margin of 35,3 per cent, or 33,4 per cent on an adjusted basis. Jewellery thus remains by far the Group’s most profitable division. Richemont points in particular to demand for established collections and new releases. This performance is also noteworthy against a backdrop of high precious metal prices. While rising raw material costs weigh on production, they can also support higher selling prices. The published figures do not indicate the extent to which revenue growth is attributable to increased sales volumes or price adjustments.
Watch brands: Significantly higher earnings
The Specialist Watchmakers are also performing positively. Their revenue rose by 10 per cent at constant exchange rates to around 1,7 billion euros. Growth accelerated to 12 per cent in the second quarter. The profit performance is particularly noteworthy: operating profit tripled year on year from 50 to 150 million euros. The operating margin reached 8,8 per cent, or 7,7 per cent adjusted for one-off effects. Richemont explicitly identifies Vacheron Constantin, Jaeger-LeCoultre and A. Lange & Söhne as key growth drivers. Their performance was supported by successful established model lines and new releases. The recovery is thus gaining firmer foundations. According to the Group, the Specialist Watchmakers have been back on a growth trajectory for more than a year. However, market conditions remain challenging: while the Americas and Japan recorded particularly strong gains, watch division revenue stagnated in Asia-Pacific. Demand in China, in particular, remains subdued. Richemont’s ability to achieve significant gains nonetheless underlines the divergent performance of regional markets and the importance of its brands’ international presence.
Direct sales continue to gain importance
Another figure is of particular interest to independent specialist retailers: direct sales to end customers through the Group’s own boutiques and online channels now account for 78 per cent of revenue. This represents an increase of two percentage points on the previous year. Richemont continues to invest in its distribution network and its own production capacity. Direct customer relationships are consequently gaining further importance within its distribution strategy. However, the Group also reports growth across its other distribution channels.
Jewellery and watches follow different trajectories
The half-year results highlight the differing financial positions of the two core businesses. Jewellery continues to generate exceptionally high margins and makes a substantial contribution to the Group’s profitability. The watch brands, by contrast, are improving their profitability from a significantly lower base. This performance will also be of interest in comparison with other luxury groups such as LVMH. However, differences in segment structures limit the scope for a direct comparison of watch and jewellery operations. Richemont itself remains cautious despite the strong results. Geopolitical and economic uncertainties persist, as do high raw material costs. With net cash of 7,7 billion euros, however, the Group has substantial resources to continue investing in its brands, distribution infrastructure and production.
Editor’s Picks